Updated October 2026 · Reviewed by Billy Forte
Texas speeding ticket insurance effects depend on your company, because the Texas Department of Insurance (TDI) says insurers charge more after tickets but leaves each company to set its own rates. No state rule says how much your premium can rise or for how long. Texas law does give one firm protection: an insurer may not raise your premium or cancel your policy because of a driving safety course dismissal.
Key Facts
- Tickets cost more: TDI says companies “will charge you more if you’ve had accidents or gotten tickets.” See what TDI says.
- No set amount: each company sets its own rates and discounts. See why there is no number.
- Records: courts report convictions to Texas DPS. Some third parties can get a 3-year conviction history. See how insurers learn.
- Course protection: an insurer may not raise a premium or cancel because of a course dismissal. See the course rule.
- Discount: TDI lists a defensive driving course as a possible discount, and each company decides the amount. See the discount.
What TDI Says About Tickets and Rates
TDI is the state agency that oversees insurance in Texas. Its auto insurance guide is direct about tickets. It says companies “will charge you more if you’ve had accidents or gotten tickets.” It adds that “some companies might refuse to sell you a policy.”
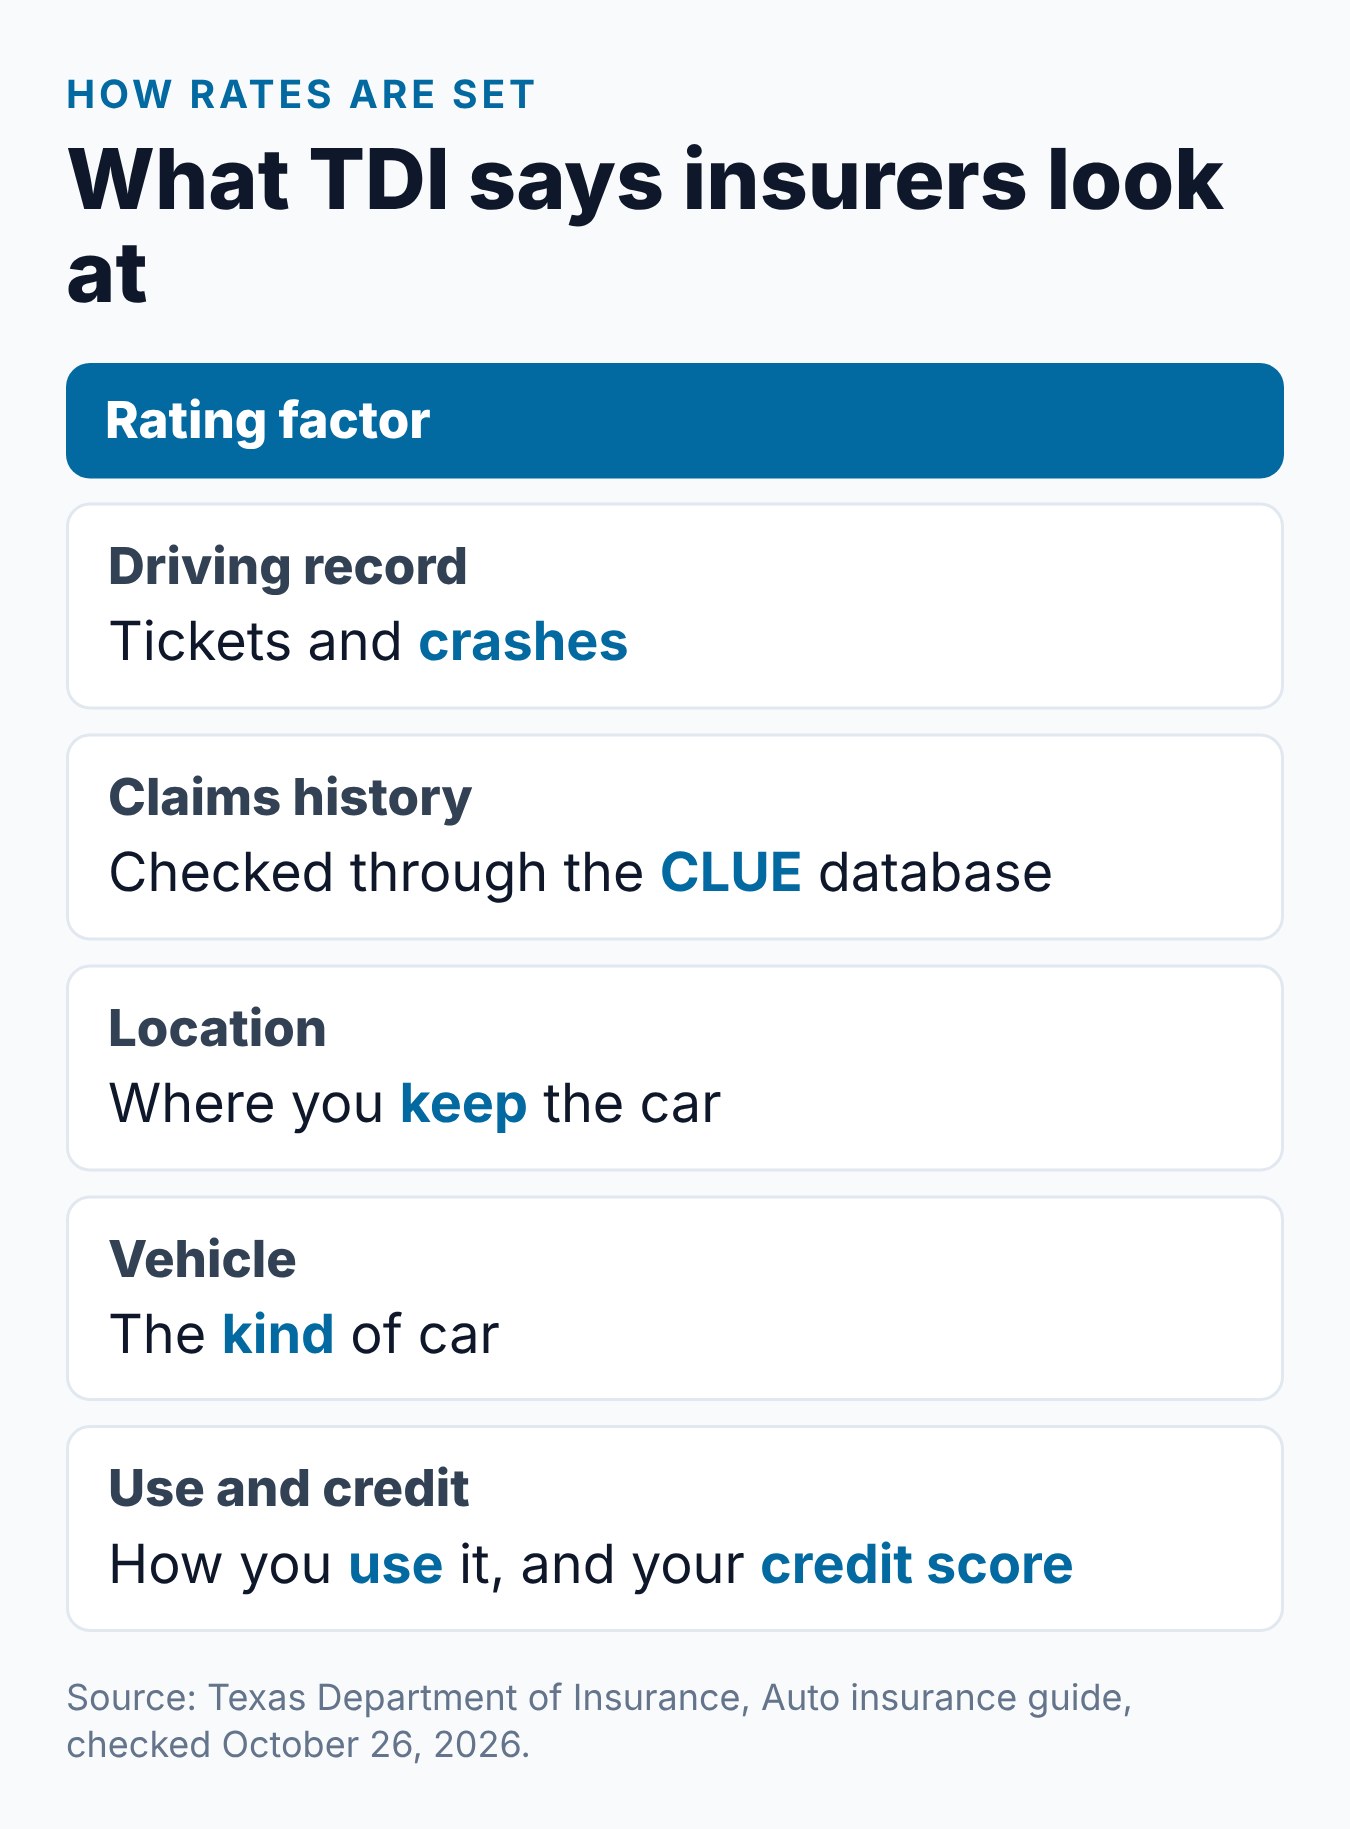
The same guide lists the main things companies look at when they set a rate:
- Your driving record and claims history.
- Where you keep your car.
- The kind of car you have.
- How you use your car.
- Your credit score.
So a ticket is one factor among several. TDI also says “most companies” use a database called CLUE to learn your claims history.
Why No One Can Give You a Number
You may see claims online that a ticket raises rates by a set amount for a set number of years. TDI does not say that. No Texas rule we found sets a percentage or a time period.
Each company writes its own rules within state law. Two companies can treat the same ticket in different ways. The only reliable answer comes from your own insurer, so ask it directly.
How an Insurer Can Learn About a Ticket
Courts do not report to insurers. They report to Texas DPS. Transportation Code Chapter 543 says the court must send a conviction record to DPS no later than the seventh day after the conviction.
Some outside parties can then get driver record data. Transportation Code Chapter 521 lets people who qualify under the state’s Motor Vehicle Records Disclosure Act get two things:
- License status, for $4.
- Moving-violation convictions and crashes with a citation from the three years before the request, for $6.
The fuller records, Type 3 and Type 3A, go only to the record owner. For more on who can see a record, read the Texas driving record background check guide.
Texas Speeding Ticket Insurance Rules for a Course Dismissal
The driving safety course path ends in a dismissal, not a conviction. Code of Criminal Procedure Chapter 45A then sets two rules.
First, a dismissed charge “may not be part of a person’s driving record or used for any purpose.” Second, an insurer may not cancel a policy or raise a premium because the driver finished the course or had the charge dismissed.
The court does report that you finished a course, and the date. Your record can show the fact of the course, but not the reason for it.
To use this path, you must qualify and ask on or before the answer date. You also need to show proof of insurance to the court. See the options guide for the full list of conditions.
Each Outcome and Your Record
How the case ends decides what reaches DPS. This table sums up what the law says for each outcome.
| How the case ends | What goes to Texas DPS | What the law says about premiums |
|---|---|---|
| You pay (guilty or no contest) | A conviction, within 7 days | TDI: companies charge more for tickets |
| Course finished, charge dismissed | Only that a course was finished, and when | No premium increase or cancellation because of it |
| Deferred, conditions met | No conviction report while deferred | Ask your insurer |
| Deferred, guilt found later | A conviction, within 7 days | TDI: companies charge more for tickets |
Under deferred disposition, the court may not send a conviction record while the case is deferred. If the judge later finds guilt, the record must go to DPS within 7 days.
The Defensive Driving Discount
TDI’s guide lists “completed a defensive driving or a driver education course” as a possible discount. It also says, “Each company decides what discounts to offer and the amount of the discount.”
TDLR’s Taking a Driving Safety Course page says the 6-hour course can be used for ticket dismissal or insurance discounts. Ask your insurer whether it offers the discount and what proof it wants.
The discount has its own guide. See the Texas driving safety course insurance discount.
Cancellation and Nonrenewal Rules
A ticket can raise worry about losing coverage. TDI’s guide sets out the general rules:
- A company must give you 10 days’ notice before it cancels.
- In the first 60 days, a company may cancel for any reason, unless that breaks a law.
- At any time, it may cancel if you stop paying premiums or file a fraudulent claim.
- A company can nonrenew only after the policy has been in effect for 12 months.
If you think a company wrongly canceled or nonrenewed your policy, you can complain to TDI. The complaint must be in writing, and TDI has an online complaint portal. TDI’s phone number for questions is 800-252-3439.
Keep Your Coverage Current
Insurance also plays a part in the course itself. Chapter 45A lists proof of financial responsibility as a condition of the course right.
TDI says Texas law requires drivers to show they can pay for crashes they cause. It names the minimum liability limits as 30/60/25. That means $30,000 per injured person, up to $60,000 per accident, and $25,000 for property damage.
If No Company Will Sell You a Policy
TDI says some companies might refuse to sell a policy to a driver with tickets. For that case, Texas has a backup. TDI says you can get basic coverage through the Texas Automobile Insurance Plan Association, called TAIPA.
Here is what TDI says about it:
- You can get TAIPA coverage if two insurance companies have turned you down.
- It sells liability, personal injury protection, and uninsured or underinsured motorist coverage.
- It does not sell collision or comprehensive coverage, or liability limits above the state minimum.
- It costs more than coverage from other companies, and it also charges more for tickets or accidents.
To apply, TDI says to talk to your agent. TDI adds that if you have TAIPA coverage and go a year without tickets or accidents, your rates might go down.
Check Your Own Records
Knowing what is on your records helps you talk to an insurer. You can order your own Texas driver record from DPS online.
A Type 2 record lists moving violations for three years and costs $6. A Type 3A record is the certified list of all crashes and violations and costs $10.
Claims history is a separate report. TDI says you can get a free copy of your CLUE report each year. For the DPS ordering steps, see how to get a Texas driving record online.
Questions to Ask Your Insurer
Your insurer is the only source for your own numbers. Bring these questions to the call:
- Will a speeding conviction change my rate, and when?
- Do you offer a discount for a defensive driving course?
- What proof of the course do you need?
- When does my policy renew?
Write down who you spoke with and the date of the call. If the answers differ from what you expected, you can compare quotes from other companies.
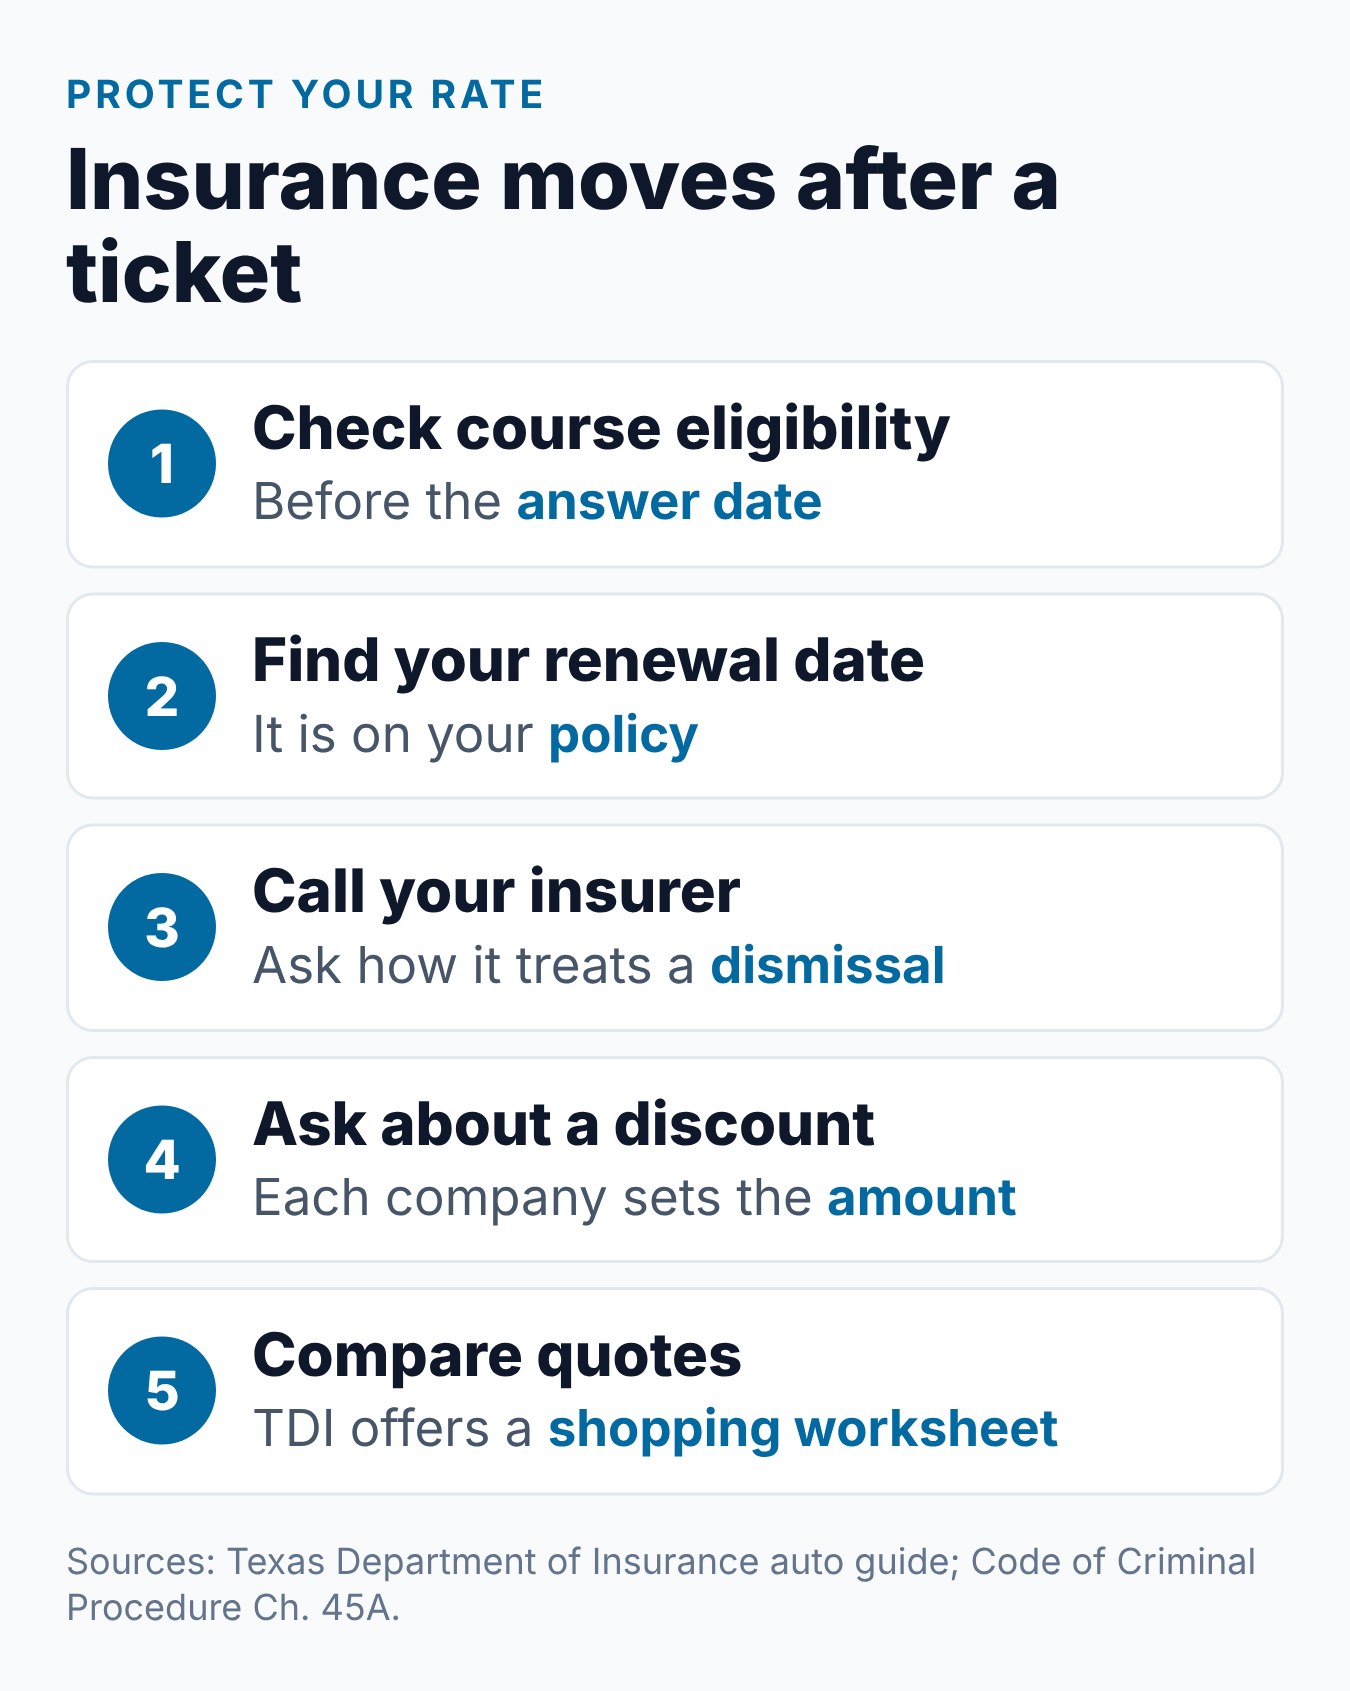
Steps to Take After a Ticket
These steps follow from the rules above:
- Check whether you qualify for the course before the answer date.
- Read your policy and note when it renews.
- Call your insurer and ask how it treats tickets and course dismissals.
- Ask whether it offers a defensive driving discount.
- If you shop for coverage, use TDI’s shopping worksheet to compare quotes.
TDI points to HelpInsure.com to find out which companies use credit scores. That can help when you compare companies.
What We Found on the TDI Guide
On the TDI auto insurance guide we checked on October 26, 2026, the page named tickets and accidents as reasons companies charge more. It did not give a percentage or a time frame for any increase.
The page listed a defensive driving course among its examples of discounts. It said each company decides which discounts to offer and how much they are worth.
Common Mistakes to Avoid
Each of these ties back to a rule above:
- Trusting a set percentage. TDI gives no number, so any fixed figure did not come from the state.
- Thinking the court calls your insurer. Courts report convictions to DPS, not to insurers.
- Paying before checking the course. Paying ends in a conviction. A course dismissal is protected from premium increases.
- Letting coverage lapse. Proof of insurance is a condition of the course right.
- Assuming a discount. Each company decides whether to offer one and how much.
How Requirements Can Vary
The driving safety course rules come from Texas law and TDLR and apply statewide. Each justice or municipal court still sets its own fees, filing steps and contact methods, and the facts of your citation decide which options you have.
Laws, fees and court procedures can change. Check your citation, ask the court that handles your case, and use the TDLR and Texas DPS websites for current rules before you act.
Frequently Asked Questions
How much will a speeding ticket raise my insurance in Texas?
There is no state figure. TDI says companies charge more for tickets, and each company sets its own rates. Ask your insurer how it treats a ticket like yours.
Does a speeding ticket insurance increase in Texas last a set time?
No state rule sets a time frame. Each company decides how it uses your driving record. Your insurer can tell you its own policy.
Can my insurer raise my rate if I take the driving safety course?
Not because of the course. Texas law says an insurer may not cancel a policy or raise a premium because you completed the course or had the charge dismissed through it.
Does the court tell my insurance company about my ticket?
No. The court reports convictions to Texas DPS. Insurers and others can get record data only if state law allows them, such as a 3-year history of moving-violation convictions.
Will the course get me a discount?
It might. TDI lists a defensive driving course as a possible discount, but each company decides whether to offer one and how much. Ask your insurer first.
What can I do if my policy is canceled?
Start shopping for new coverage right away, as TDI advises. If you think the cancellation was improper, you can file a written complaint with TDI.
What is TAIPA?
It is the Texas Automobile Insurance Plan Association. TDI says you can get basic coverage there if two insurance companies have turned you down. TDI also says it costs more than coverage from other companies.
Conclusion
TDI says tickets raise rates, but each company sets its own amount and time frame. A conviction goes to Texas DPS, while a course dismissal is shielded by law from premium increases.
Ask your insurer about its rules and any discount before you decide on your ticket. If you qualify for the course, Driving Logic’s online Texas driving safety course is one option to look at.
Related Articles
- Texas Speeding Ticket: Costs, Record Impact, and What to Know
- Texas Defensive Driving Insurance Discount: What to Know
- Texas Speeding Ticket Options: Pay, Contest, or Take Defensive Driving
- Texas Driving Record Background Check: What Employers and Insurers See
Sources
- Texas Department of Insurance — Auto insurance guide
- Texas Code of Criminal Procedure Chapter 45A (PDF)
- Texas Transportation Code Chapter 543 — Arrest and Prosecution of Violators (PDF)
- Texas Transportation Code Chapter 521 — Driver’s Licenses (PDF)
- TDLR — Taking a Driving Safety Course
Billy Forte is the owner of Driving Logic, a state-approved driver improvement course provider serving Texas and other U.S. states.
This article is general information, not legal advice. Texas traffic and driving safety course rules are set by Texas law, TDLR, Texas DPS and each court, and they can change. Check with the court on your citation and the official TDLR and DPS websites for current requirements, and talk to a Texas lawyer about your specific case.